No.4201
Imported Luxury Brand Market in Japan: Key Research Findings 2026
Japan’s Imported Luxury Brand Retail Market Fell 1.6% YoY in 2025, First Decline in Five Years, as Stronger Yen Slows Inbound Tourism
Yano Research Institute (the President, Takashi Mizukoshi) carried out a survey on the imported luxury brand market in Japan and found out the current status, brand trends, and future perspectives.
Market Overview
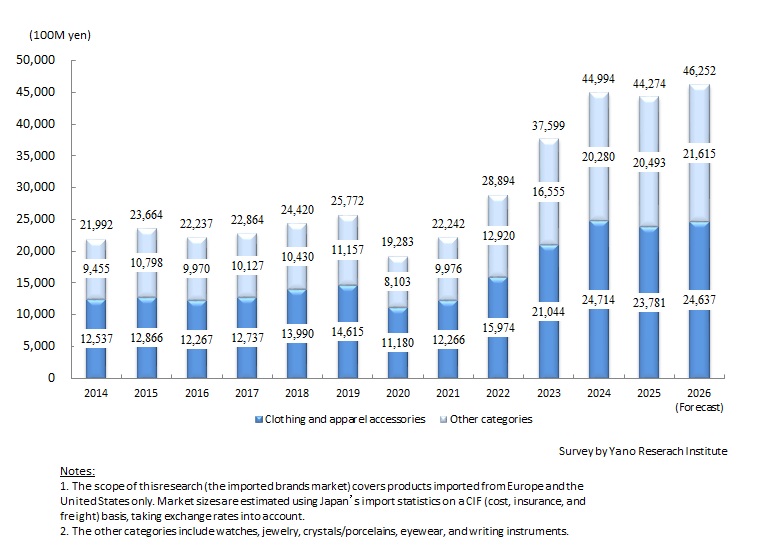
The market size of Japan’s imported luxury brand retail in Japan is estimated at 4,427,400 million yen. The market indicated 1.6% decline from the previous year, which is for the first time in five years after the pandemic. The downturn was driven primarily by a sharp drop in inbound demand; however, this decline was largely offset by steady consumption among domestic high-net-worth individuals.
According to the Japan National Tourism Organization (JNTO), international visitor arrivals to Japan rose 15.8% year on year to 42.7 million in 2025, surpassing 40 million for the first time. However, exchange rate fluctuations dampened visitor spending. In April, the yen briefly strengthened against the U.S. dollar compared to the start of the year, triggering a sharp drop in inbound demand. Although the currency resumed its depreciation by autumn, the recovery was insufficient to offset the losses sustained in the first half of the year.
Noteworthy Topics
Consumers Shifting to Jewelry Amid Price Hikes
Product price hikes continued into 2025, driven by the weak yen as well as surging raw material, labor, and transportation costs stemming from the COVID-19 pandemic. Against this backdrop, the brands covered by this survey raised their prices by an average of 10 percent, with the increases ranging from 5% to15%. Jewelry brands generally implemented the largest increases.
Meanwhile, a growing segment of consumers is prioritizing investment pieces over trend-driven items, opting for jewelry rather than iconic designer bags. As a result, the bags and small leather goods segment—the largest product category in the import brands market—declined for the first time in five years, while the jewelry segment recorded its fifth consecutive years of growth. Recognizing this opportunity, jewelry brands are intensifying their efforts, while other luxury brands are rapidly expanding their jewelry lines. This trend is expected to continue into 2026.
Future Outlook
The imported luxury brand retail market in Japan (15 product segments) is projected to grow by 4.5% year on year to reach 4.6 trillion yen (4,625,200 million yen) in 2026.
Spending by affluent consumers in Japan is projected to remain resilient, alongside a recovery in inbound tourism demand. Rising visitor arrivals from Southeast Asia, the Middle East, Europe, and North America are contributing to a more geographically diverse customer base for luxury goods.
On the retail side, major renovations of luxury floors at leading department stores, together with a succession of large-scale retail complex openings, are expanding and upgrading the luxury retail landscape. Meanwhile, creative director changes at major brands are expected to stimulate currently subdued demand for bags and apparel.
Given the situation, the market is expected to grow moderately for the next few years.
Research Outline
2.Research Object: Trading firms, manufacturers, and retailers of clothing, accessories, watches, jewelry, crystals, bone chinaware, porcelains, eyewear, and writing instruments produced by the European and the U.S. brands, and Japanese subsidiaries of such brands
3.Research Methogology: Face-to-face interviews (including online interviews) by our expert researchers, survey via telephone, and literature research
Imported Luxury Brands Market
The scope of this research (the imported brands market) covers products imported from Europe and the United States, which are divided into the 15 segments outlined below:
1) womenswear, 2) menswear, 3) infant & baby clothing, 4) bags and SLGs, 5) shoes, 6) ties, 7) textile accessories (including scarves, shawls, and handkerchiefs), 8) leatherwear, 9) belts, 10) gloves, 11) watches, 12) jewelries, 13) crystals, chinaware, and porcelains, 14) eyewear, and 15) writing instruments.
<Products and Services in the Market>
1) Womenswear, 2) Menswear, 3) Infant & Baby Clothing, 4) Bags & SLGs, 5) Shoes, 6) Ties, 7) Textile Accessories (Including Scarves, Shawls, And Handkerchiefs), 8) Leatherwear, 9) Belts, 10) Gloves, 11) Watches, 12) Jewelries, 13) Crystals, Chinaware, & Porcelains, 14) Eyewear, and 15) Writing Instruments
Published Report
Contact Us
The copyright and all other rights pertaining to this report belong to Yano Research Institute.
Please contact our PR team when quoting the report contents for the purpose other than media coverage.
Depending on the purpose of using our report, we may ask you to present your sentences for confirmation beforehand.